Small business professional insurance, a safety net for the visionaries and risk-takers who drive our economy, is an intricate tapestry of coverage options, risk management strategies, and legal compliance. Dive into this comprehensive guide to safeguard your business and dreams.
Navigating the complexities of insurance can be daunting, but we’re here to break down the jargon and empower you with knowledge. From general liability to professional negligence, property protection to business interruption, we’ll explore the insurance landscape tailored specifically for small business professionals.
Coverage Options
Small business professionals face a wide range of risks that can impact their operations and financial well-being. Comprehensive insurance coverage is essential to mitigate these risks and protect their businesses.
Various types of insurance coverage are available, each designed to address specific needs and provide protection against different types of losses. Understanding the different options and selecting the appropriate coverage is crucial for small business professionals.
General Liability Insurance, Small business professional insurance
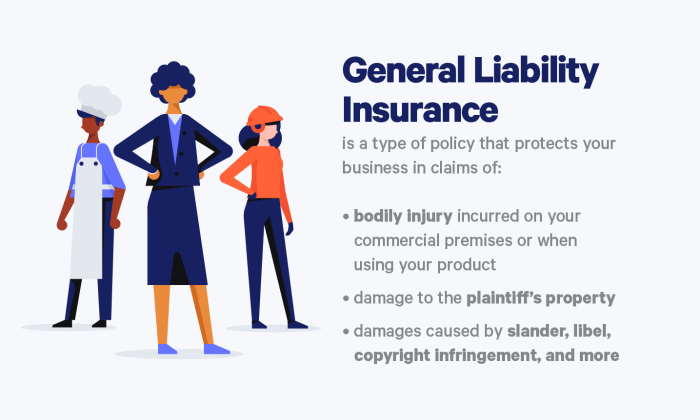
General liability insurance protects businesses against claims of bodily injury, property damage, or personal injury caused by their operations, products, or services. It covers legal expenses, settlements, and judgments arising from third-party claims, such as:
- Customer injuries on business premises
- Product defects causing harm
- Professional negligence
Professional Liability Insurance
Professional liability insurance, also known as errors and omissions (E&O) insurance, protects businesses against claims of negligence, errors, or omissions in their professional services. It covers legal expenses, settlements, and judgments arising from claims that the business failed to meet the expected standard of care in providing its services, such as:
- Mistakes in professional advice
- Breach of contract
- Intellectual property infringement
Property Insurance
Property insurance protects businesses against physical damage or loss to their property, such as buildings, equipment, inventory, and other assets. It covers losses due to events like fire, theft, vandalism, natural disasters, and other covered perils, such as:
- Building damage from a storm
- Theft of office equipment
- Fire damage to inventory
Business Interruption Insurance
Business interruption insurance provides coverage for lost income and expenses incurred when a business is unable to operate due to a covered event, such as a natural disaster, fire, or equipment failure. It helps businesses maintain financial stability during periods of disruption, such as:
- Loss of revenue due to a hurricane
- Closure due to a fire
- Downtime caused by a cyberattack
Risk Assessment and Mitigation
Risk assessment is a crucial step for small businesses to identify and understand potential threats that can jeopardize their operations. By conducting a thorough risk assessment, businesses can proactively mitigate risks and safeguard their assets, reputation, and financial stability.
Effective risk mitigation strategies involve implementing safety protocols, training employees, and maintaining proper documentation. These measures help businesses minimize the likelihood and impact of potential incidents, ensuring a safer and more secure work environment.
Risk Assessment
- Identify potential risks:Conduct a comprehensive review of operations, processes, and assets to pinpoint areas vulnerable to threats such as accidents, data breaches, or natural disasters.
- Assess risk severity and likelihood:Evaluate the potential impact and probability of identified risks, prioritizing those that pose the greatest threat to the business.
- Develop risk mitigation plans:Create specific plans outlining actions to reduce or eliminate identified risks, including emergency response protocols, cybersecurity measures, and employee safety training.
Risk Mitigation
- Implement safety protocols:Establish clear safety guidelines, conduct regular inspections, and provide necessary safety equipment to prevent accidents and protect employees.
- Train employees:Educate employees on identified risks and their roles in risk mitigation, empowering them to make informed decisions and respond effectively to potential threats.
- Maintain proper documentation:Keep accurate records of risk assessments, mitigation plans, and incident reports to demonstrate compliance and provide evidence for insurance claims if necessary.
Claims Process
Filing an insurance claim for small business professionals is a crucial process that can help mitigate financial losses and ensure business continuity. Here’s a detailed overview of the steps involved:
When a covered event occurs, it’s essential to promptly notify your insurance company. Most policies require you to report claims within a specific timeframe, usually within 30-60 days. You can initiate the claim process by calling your insurance provider or submitting a claim online.
Documenting Your Claim
To support your claim, you will need to provide comprehensive documentation. This may include:
- A detailed description of the incident, including the date, time, and location
- Photographs or videos of the damage or loss
- Receipts and invoices for any expenses incurred due to the incident
- Contact information for witnesses or other parties involved
Timelines and Processing
The claims processing timeline can vary depending on the complexity of the claim and the insurance company’s procedures. Generally, you can expect the following steps:
- Initial Review:The insurance company will review your claim and request any additional documentation needed.
- Investigation:An adjuster may be assigned to investigate the claim and assess the extent of the damage or loss.
- Settlement Offer:Once the investigation is complete, the insurance company will make a settlement offer based on the policy coverage and the evidence provided.
- Negotiation and Approval:You can negotiate the settlement offer with the insurance company if you believe it is inadequate. Once an agreement is reached, the claim will be approved.
- Payment:The insurance company will issue payment for the approved claim amount.
Tips for Effective Communication
To maximize your claim payout and ensure a smooth claims process, consider the following tips:
- Be clear and concise:Provide accurate and detailed information about the incident and your losses.
- Document everything:Gather all relevant documentation and keep it organized for easy reference.
- Stay organized:Maintain a file or folder for all claim-related correspondence and documents.
- Be patient:Claims processing can take time, so be patient and follow up regularly without being overly demanding.
- Consider professional help:If you have a complex or high-value claim, consider seeking advice from an insurance attorney or claims adjuster.
Choosing the Right Insurance Provider: Small Business Professional Insurance
Selecting the right insurance provider is crucial for small business professionals. Consider these factors:
Coverage Options:Ensure the provider offers comprehensive coverage tailored to your specific risks.
Premiums:Compare premiums from multiple providers to find the best value for your budget.
Customer Service:Look for a provider with a reputation for responsive and helpful customer support.
Negotiating with Insurance Providers
Negotiate effectively to secure the best coverage at a competitive price:
- Shop around:Obtain quotes from several providers to compare coverage and premiums.
- Bundle policies:Combine multiple policies, such as general liability and professional liability, with the same provider to save money.
- Increase deductibles:Consider raising your deductibles to lower premiums, but ensure you can afford the higher out-of-pocket costs.
- Ask for discounts:Inquire about any available discounts, such as those for good safety records or professional certifications.
Legal and Regulatory Compliance
Ensuring compliance with legal and regulatory requirements is essential for small business professionals. Maintaining adequate insurance coverage not only protects your business but also fulfills legal obligations and safeguards your financial interests.
Consequences of Inadequate Insurance
Failing to maintain adequate insurance can have severe consequences:
- Financial losses due to uninsured events
- Legal liability for accidents or injuries
- Reputational damage
- Difficulty obtaining financing or contracts
Compliance with Industry Standards
To stay compliant, small business professionals should:
- Understand the specific insurance requirements for their industry
- Review industry best practices and standards
- Seek guidance from insurance professionals and legal counsel
By adhering to these guidelines, small business professionals can ensure they meet their legal and regulatory obligations, protect their assets, and maintain their business’s reputation and financial stability.
Final Wrap-Up
As you navigate the ever-changing business landscape, small business professional insurance stands as a beacon of protection, ensuring your enterprise weathers the storms and seizes opportunities. By understanding your risks, selecting the right coverage, and staying compliant, you’re not just safeguarding your business; you’re investing in its future success.
General Inquiries
What types of coverage does small business professional insurance offer?
Small business professional insurance typically includes coverage for general liability, professional liability, property damage, business interruption, and employee-related risks.
How can I assess my business’s risks?
Conduct a thorough risk assessment by identifying potential hazards, evaluating their likelihood and impact, and implementing measures to mitigate them.
What are the key factors to consider when choosing an insurance provider?
Compare coverage options, premiums, customer service, financial stability, and industry reputation to select the provider that best meets your needs.